A personal loan can be a useful financial option when you need funds for a major expense, emergency, education, home improvement, medical costs, or other planned needs. Since personal loans are usually unsecured, borrowers do not generally need to provide an asset as collateral.
At LendSmart, we offer personalised mortgage solutions to make the home-buying process simpler and more manageable. With competitive rates, flexible loan options, and professional guidance at every stage, we help you find a mortgage that suits your budget, financial circumstances, and homeownership goals.
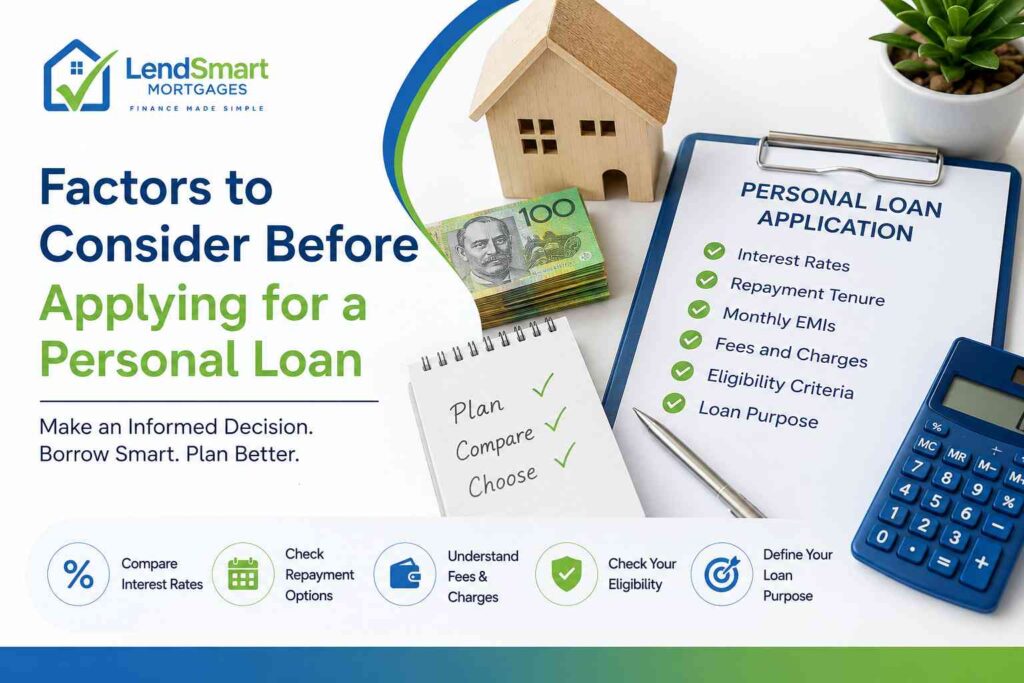
Taking time to compare your options can help you avoid unnecessary financial pressure. Whether you are applying for your first personal loan or considering another loan, several factors deserve careful attention.
Understand Why You Need the Loan
The first step is to clearly identify why you need to borrow money. A personal loan can provide quick access to funds, but borrowing without a clear purpose can make it easier to take on unnecessary debt. Consider whether the expense is urgent, planned, or something that could be postponed until you have enough savings.
Understanding the purpose of the loan also helps you decide how much you actually need. Instead of borrowing the maximum amount available, calculate the exact amount required. Borrowing less can reduce both your monthly repayment and the total interest paid over the loan term.
Check Your Credit Score
Your credit score is an important factor that lenders may consider when evaluating a personal loan application. It provides an indication of your previous borrowing and repayment behaviour. A strong credit history can improve your chances of approval and may help you qualify for more favourable loan terms.
Before applying, check your credit report for errors or outdated information. If you have existing loans or credit cards, make sure your repayments are being made on time. It is also useful to avoid applying for multiple loans or credit products within a short period, as numerous applications may affect how lenders assess your credit profile.
Compare Interest Rates
The interest rate is one of the most important factors to consider because it directly affects the cost of borrowing. Even a small difference in the interest rate can make a noticeable difference when a loan is repaid over several years.
Do not simply choose the first lender that offers you a loan. Compare rates from different financial institutions and understand whether the advertised rate is the rate you are actually eligible to receive. Your income, credit history, loan amount, and repayment period can influence the rate offered to you.
Consider the Loan Tenure
Loan tenure refers to the period over which you will repay the borrowed amount. A longer tenure generally means smaller monthly instalments, but you may pay more interest over the entire loan period. A shorter tenure can increase your monthly repayment while potentially reducing the total interest cost.
The right tenure depends on your income and existing financial commitments. Choose a repayment period that allows you to manage your monthly expenses comfortably without creating unnecessary financial pressure.
Calculate Your Monthly EMI
Before applying, calculate the expected monthly instalment, commonly known as EMI. Your EMI should fit comfortably within your regular budget after considering rent, household expenses, existing loan repayments, savings, and other financial commitments.
A loan may appear affordable when looking only at the total amount you can borrow. However, the monthly repayment determines how the loan will affect your everyday finances. Planning your EMI in advance can help you determine whether the proposed loan amount and tenure are realistic.
Check Your Eligibility
Every lender has its own eligibility criteria. These may include age, employment status, income, credit history, residency requirements, and other financial conditions. Some lenders may also have minimum income requirements or restrictions based on employment type.
Checking eligibility before submitting an application can save time and reduce the chances of rejection. Review the lender’s requirements carefully and make sure the information provided in your application is accurate and consistent with your supporting documents.
If you’re searching for a dependable Home Loan Adelaide, LendSmart Mortgages provides tailored lending solutions based on your financial circumstances and homeownership plans. With competitive rates, flexible mortgage options, and expert guidance, we help make the home loan journey straightforward and stress-free, from initial application through to settlement.
Understand All Fees and Charges
The interest rate is not the only cost associated with a personal loan. Depending on the lender and loan agreement, you may encounter processing fees, documentation charges, late payment fees, prepayment or foreclosure charges, and other applicable costs.
Before accepting a loan, read the complete fee structure instead of focusing only on the interest rate. Understanding these charges gives you a clearer picture of the actual cost of borrowing and helps you compare different loan offers more effectively.
Review the Loan Agreement Carefully
A loan agreement contains important information about the borrowing arrangement, including the loan amount, interest rate, repayment schedule, fees, penalties, and conditions for early repayment. It is important to read these terms carefully before signing.
Do not rely only on verbal explanations or promotional information. If there is something you do not understand, ask the lender for clarification. Pay particular attention to repayment conditions, late payment consequences, and any charges that may apply if you decide to repay the loan early.
Consider Your Existing Debts
Your current financial obligations should be considered before taking on another loan. If you already have credit card balances, home loans, vehicle loans, or other personal loans, adding another monthly repayment could put pressure on your budget.
Look at your overall debt rather than evaluating the new loan in isolation. If a significant portion of your monthly income is already committed to debt repayments, consider whether taking another loan is necessary. Responsible borrowing means making sure you can handle the new obligation alongside your existing commitments.
Check Your Income Stability
Income stability is another important consideration. A personal loan creates a fixed repayment obligation, so you need to be reasonably confident that you can continue making payments throughout the loan term.
If your income varies significantly from month to month, consider this when deciding how much to borrow. Building an emergency fund can also provide some protection against unexpected expenses or temporary income disruptions.
Avoid Borrowing More Than You Need
Lenders may offer you a loan amount that is higher than the amount you initially planned to borrow. While having access to additional funds may seem attractive, taking more money than necessary increases your repayment obligation and total borrowing cost.
Instead, calculate the amount required for your specific purpose and borrow accordingly. Keeping the loan amount under control can make repayment easier and reduce the amount of interest you pay.
Compare Lenders Before Making a Decision
Different lenders can offer different interest rates, loan amounts, repayment periods, fees, and customer service experiences. Comparing these factors can help you find an option that matches your financial situation.
Look beyond advertisements and introductory offers. Consider the complete cost of the loan, eligibility requirements, repayment flexibility, processing time, and the lender’s terms and conditions. A loan with a slightly lower advertised rate may not always be the cheapest option if it comes with significant additional charges.
Have Your Documents Ready
Personal loan applications commonly require documents that verify your identity, income, employment, and financial information. Requirements vary between lenders, so check what documents are needed before applying.
Having accurate and up-to-date documents ready can make the application process smoother. Make sure that the information on your application matches the information in your supporting documents to avoid unnecessary delays.
Think About Your Long-Term Financial Plans
Finally, consider how the loan fits into your broader financial plans. A personal loan should not interfere significantly with important goals such as building savings, investing, paying existing debts, or managing regular household expenses.
Before applying, ask yourself whether the repayment will remain manageable if your expenses increase. Looking beyond the immediate need for money can help you make a more responsible borrowing decision.
Make an Informed Borrowing Decision
Applying for a personal loan is an important financial decision, even when the application process is quick and convenient. Understanding your purpose for borrowing, checking your credit profile, comparing interest rates, calculating the EMI, reviewing fees, and assessing your existing debts can help you choose more carefully.
The goal should not simply be to find a lender willing to approve your application. It should be to find a loan that you can comfortably repay without putting unnecessary pressure on your finances. By reviewing the terms carefully and borrowing only what you genuinely need, you can make personal borrowing a more manageable part of your overall financial plan.